Credit Scores: What the Number Really Measures
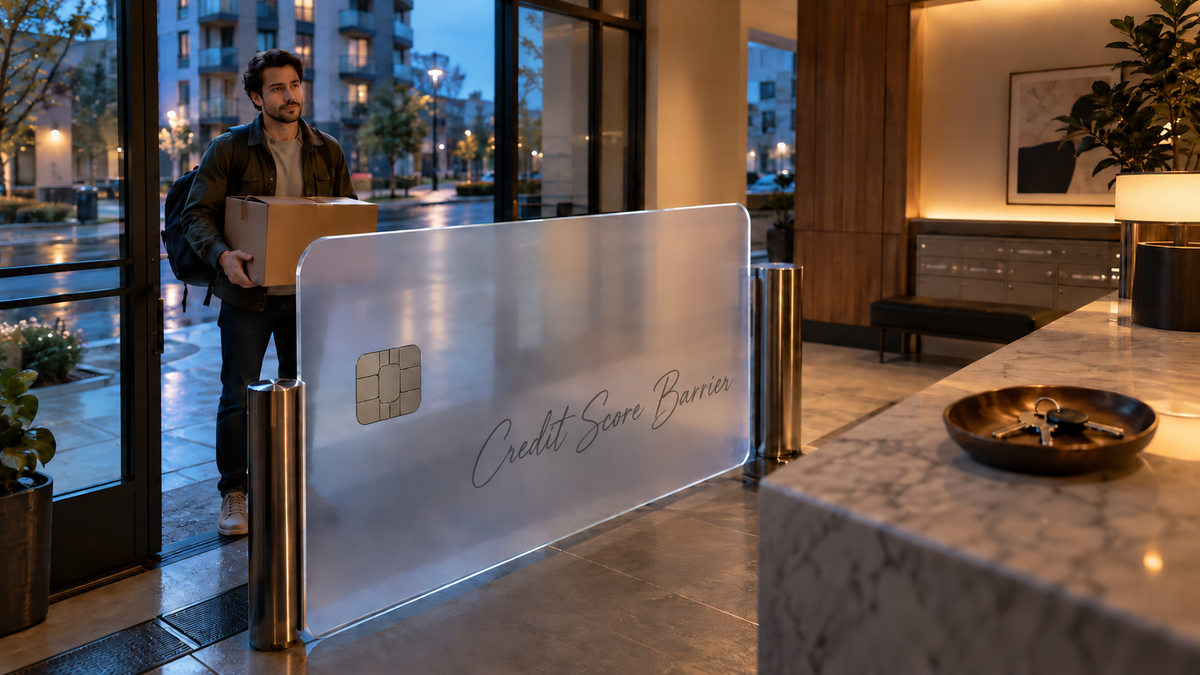
It looks like a measure of financial health, but it was built to answer a much narrower question. A credit score feels like a grade. The higher it climbs, the more financially responsible we appear to be. A lower score can feel like evidence that we’ve failed some basic test of adulthood. We celebrate when it rises and worry when it falls. But what, exactly, is being graded? The answer is narrower than most of us have been led to believe. A credit score does not measure wealth, income, savings, cash flow, job security, or whether someone is living within their means. According to FICO’s own explanation, its scores are calculated from credit reports, primarily using payment history, amounts owed, length of credit history, credit mix, and new credit. In other words, the score does not measure financial health. It measures how a person has managed reported credit. A Tool Built for Lenders The Consumer Financial Protection Bureau describes a credit score as a prediction of credit behavior, including the likelihood that a borrower will repay a loan on time. That is its real and legitimate purpose. A lender considering thousands or millions of applications needs a reasonably consistent way to estimate risk. This means a credit score was never designed primarily for the consumer. It was built to answer a lender’s question: How likely is this applicant to repay us as agreed? That is not necessarily sinister. Lending involves risk, and a reasonably accurate scoring system can make decisions faster, reduce some individual bias, and help reliable borrowers qualify for better terms. The confusion begins when we turn that limited risk estimate into a broad judgment about financial success. A person can have substantial savings and little recent credit activity. Another can have modest savings, several open accounts, a mortgage, and a car payment while maintaining an excellent score. The second person offers more evidence of how they handle debt, but is not automatically more secure. The score knows the relationship with lenders. It does not know the whole person. Where the Skepticism Is Justified Credit scoring also exists inside a profit-making system. Lenders use scores to approve applications and set interest rates, credit limits, and other terms. Credit reporting companies provide consumer information to businesses making decisions about credit, housing, insurance, and other services. The score itself is not a direct measure of how profitable a customer will be. It does not calculate how much interest someone has paid or how easily that person can be persuaded to borrow more. Calling it a “profitability index” goes farther than the evidence supports. Still, it is a risk-management tool used inside a system built to make money from lending. A strong score identifies someone who appears likely to repay. That makes the person an attractive potential customer and may lead to larger credit limits and more offers. Those offers can be useful, but they also expand the opportunity to borrow. Even customers who pay credit cards in full can generate revenue for issuers through transaction fees. A Federal Reserve Bank of Richmond overview explains how interchange fees flow from merchants through the payment network to card issuers. Carrying a balance and paying interest are not required to build a strong score, and the CFPB specifically advises that consumers do not need outstanding debt to maintain good credit. That distinction matters. The system rewards the responsible use of available credit, but it does not require financial independence from credit. It can tell lenders that we are dependable borrowers. It cannot tell us whether borrowing is improving our lives. When a Risk Score Becomes a Social Score The number now reaches beyond the original lending decision. Credit information can affect apartment applications, insurance pricing, security deposits, and major purchases. A tool created to estimate loan risk has become a gatekeeper for ordinary life. That gives the score psychological power. People can begin protecting the number as though it were the goal. Paying off an installment loan can sometimes cause a temporary decline because the account mix has changed. That can feel like punishment even though eliminating debt may improve cash flow and reduce interest costs. There is another concern: the system depends on the accuracy of enormous amounts of reported data. An FTC study found that about one in five participants identified an error in at least one credit report, and about 5 percent had errors serious enough that correcting them placed the consumer in a different credit-risk category. When a number controls access, even a small error can become expensive. Use the Score Without Worshipping It None of this makes credit scores useless. If you expect to finance a home or vehicle, rent an apartment, or apply for credit, the score can matter greatly. Monitoring reports, correcting errors, paying on time, and keeping revolving balances low are sensible forms of financial maintenance. But maintenance is not the same as devotion. True financial stability is better measured by what the score leaves out: reliable income, manageable expenses, emergency savings, growing assets, declining liabilities, and the ability to absorb a setback. Net worth measures what we own after subtracting what we owe. Cash flow shows whether our financial life works month to month. Neither can be reduced to a three-digit estimate of lender risk. This is not really about whether credit scores are good or bad. It is about mistaking a tool designed for lenders a verdict on ourselves. And that matters because once we understand what the number measures, we can use it when necessary without allowing it to define financial success. A good credit score can help us borrow. But, real financial health gives us the freedom to decide whether we actually need to.